The insurance quote belongs in your budget before the deadline, not after. Most buyers treat coverage as paperwork they will deal with a week before closing. Out here, on an older house in Syracuse or a place with two outbuildings outside Weeping Water, that is the item that can change your whole number. Or tell you the house is harder to insure than anyone mentioned.
So we get a real quote early. On the actual property. Not a ballpark, not a guess off a website.
Why this matters more east of Lincoln
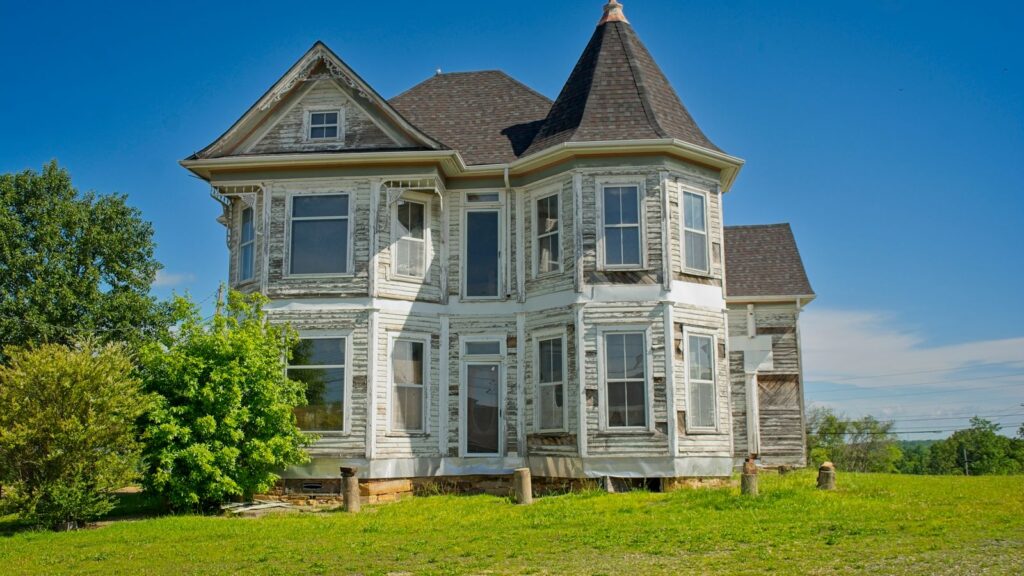
The homes in Unadilla, Palmyra, Murdock, Elmwood, Louisville and Bennet are a different animal than a 2015 build in southeast Lincoln. A lot of them are wonderful and solid and have been standing for a hundred years. They also have older roofs, older wiring, older service panels, wood stoves, fuel tanks, well and septic systems, and shops or barns that nobody has inventoried in decades.
Carriers care about all of that. They also care about things you cannot change, like how far the property sits from a fire hydrant or a staffed station. A house four miles out of town is not the same risk as a house three blocks off Main Street, even if the houses look identical.
None of that is a reason to walk away. It is a reason to know before your inspection and financing deadlines run out.
What to actually ask a licensed provider
I am not an insurance agent and I will never pretend to be. What I can tell you is what to put in front of one. Call a licensed provider, give them the exact address, and ask:
- Is this replacement cost or actual cash value? On an older roof, those two answers lead to very different outcomes after a hailstorm.
- How many deductibles am I carrying? Wind and hail is often separate from everything else in Nebraska. Ask how that one is calculated.
- What is excluded? Water backup, sewer backup, sump failure, mold, foundation movement, and anything tied to a wood-burning stove are common gaps.
- How are the outbuildings covered? Other structures coverage is usually a percentage of the dwelling amount. If your shop or barn matters to you, say so out loud and get it scheduled properly.
- Does the roof age trigger anything? Some carriers restrict coverage past a certain age. That answer can reshape your inspection negotiation.
- Are there any insurability flags? Knob and tube wiring, fuse panels, aluminum branch wiring, buried fuel tanks, or an unused well can all require work before a carrier will write it.
- Is a roof inspection or four-point inspection required? If yes, that takes calendar days you have to plan for.
Write the answers down. You are going to want them later.
Coordinate the timing with your lender and your contract
Here is the part people miss. Your contract has deadlines. Your lender has a timeline. Insurance sits in the middle of both.
The quote drives your escrow, which drives your payment, which drives what your lender says works for you. If coverage comes back heavier than expected, you want to find that out while your inspection and financing contingencies are still alive, not three days before closing when every option left is a bad one.
So the order I like: get the property under contract, order the inspection, and call your insurance provider the same week. Give your lender the real quote as soon as you have it so your numbers are honest. If the inspection turns up a roof, a panel, or an outbuilding issue, you now have two independent sources telling you the same thing. That is leverage, and it is accurate leverage.
I have watched this change a deal
I had buyers leaving a Lincoln starter home for a small-town place they genuinely wanted. The house needed work, and the roof was the fight. The sellers said no. More than once. What moved it was not pressure. It was information, inspection findings, contractor quotes, and a clear picture of what coverage looked like with that roof still on the house. We stayed patient, kept going back, and eventually got the roof negotiated in. At the same time we were prepping and listing their Lincoln house so both sides could line up. It worked because nothing was a surprise at the end.
If the quote comes back rough
You have options, and none of them are panic. Shop a second and third carrier, because they do not all read an older property the same way. Price the repair that unlocks better coverage and ask the seller to address it. Adjust what you are willing to pay to match the real cost of owning the place. Or decide this particular property is not the one.
That last one is a legitimate answer. We do not have to force it. There will be another one if it is not right. Love where you live.
The short version
- Call a licensed provider the same week you order the inspection.
- Quote the exact house and the exact outbuildings, not something comparable down the road.
- Ask about coverage type, deductibles, exclusions and insurability flags.
- Hand the real quote to your lender before your contingency deadlines close.
If you are looking at an older home or an acreage in Cass or Otoe County, reach out and we will build the timeline before you are ever under contract. Knowing the true cost of a house early is how you buy it with your eyes open.
If you’re juggling a sell and a buy at the same time, or eyeing a move to the small towns east of Lincoln, this is exactly what I do all day: See how I work →